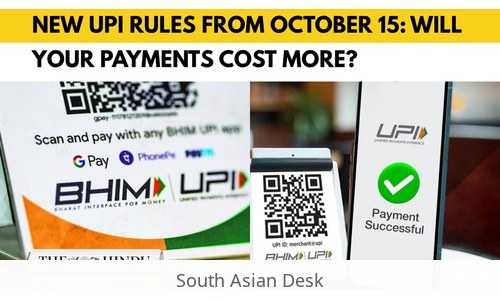
The introduction of UPI MDR charges from October 15 has sparked significant discussion about the financial implications for merchants and consumers in India’s digital payments landscape. As reported by The Hindu and NDTV, these changes will affect transactions exceeding ₹2,000, introducing a new layer of complexity to the UPI payment ecosystem. The Hindu highlighted that certain merchant categories will face a Merchant Discount Rate (MDR) of 0.4% on such transactions, while NDTV noted that railways, telecom services, insurance, and fuel merchants will incur a flat ₹5 fee. These UPI payment changes raise critical questions about cost distribution and the broader impact on consumer spending UPI and merchant strategies UPI.
UPI MDR charges: Impact on Consumer Spending
The new UPI MDR charges could significantly influence consumer behavior in the digital payments India sector. While The Hindu indicated that customers may not directly bear the cost for certain transactions, the indirect effects—such as potential price hikes by merchants—could alter spending patterns. For instance, high-value transactions above ₹2,000 may see increased scrutiny from consumers, who might opt for alternative payment methods or adjust their purchasing habits. This shift could be particularly pronounced in sectors like retail and e-commerce, where UPI has become a dominant mode of transaction. Understanding these UPI payment changes is crucial for both consumers and businesses to navigate the evolving digital economy.
Consumers may also face indirect costs through higher product prices or service fees, as merchants absorb the MDR charges into their pricing models. For example, a customer purchasing a ₹3,000 smartphone via UPI might encounter a slight price increase if the merchant passes on the MDR cost. However, The Hindu noted that for some transactions, the cost may remain borne by the merchant, depending on the nature of the service or product. This ambiguity could lead to confusion among consumers, necessitating clearer communication from both merchants and payment platforms.
Merchant Preparation for New Charges
Merchants in affected categories—railways, telecom, insurance, and fuel—face a ₹5 flat fee on UPI payments exceeding ₹2,000. This financial burden may compel them to adopt various merchant strategies UPI, such as adjusting pricing models, offering discounts for non-UPI transactions, or implementing cost-sharing mechanisms with customers. Smaller merchants, in particular, may need to reassess their operational frameworks to mitigate the impact of these UPI MDR charges.
For instance, fuel stations might introduce a slight discount for cash or card payments to offset the ₹5 fee on UPI transactions. Similarly, telecom providers could bundle services with non-UPI payment options to reduce the financial strain. Larger corporations, such as railways, may absorb the cost internally, given their scale and pricing power. However, smaller businesses with thin margins may struggle to absorb these costs without raising prices, potentially reducing their competitiveness in the digital payments India market.
The challenge lies in balancing compliance with the new regulations while maintaining competitiveness in a market where digital payments India are rapidly expanding. Merchants must also consider the customer experience, ensuring that any changes in pricing or payment methods do not deter users from adopting UPI, which remains a preferred mode of transaction for its convenience and speed.
Broader Implications for the Digital Economy
The introduction of UPI MDR charges reflects a broader trend in India’s financial infrastructure, where the government and regulatory bodies are working to ensure sustainable growth of digital transactions. While the immediate focus is on cost distribution, the long-term effects could influence the adoption of UPI as a payment method. For instance, if merchants pass on the costs to consumers, it might lead to a decline in UPI usage for high-value transactions. Conversely, if merchants absorb the costs, it could strain their profit margins, especially in sectors with thin margins.
This dynamic underscores the need for a balanced approach that supports both consumer convenience and merchant viability. The Reserve Bank of India (RBI) and the National Payments Corporation of India (NPCI) have emphasized the importance of maintaining UPI’s appeal as a seamless and cost-effective payment method. However, the new charges may test this balance, requiring continuous monitoring and potential adjustments to the MDR framework.
The broader implications extend to India’s digital economy, which has seen rapid growth in UPI transactions. If the MDR charges lead to a decline in high-value UPI transactions, it could slow the pace of digital adoption in certain sectors. Conversely, if the charges are managed effectively, they could reinforce the stability of the UPI ecosystem by ensuring that the costs are distributed fairly among stakeholders.
Conclusion
As UPI MDR charges take effect from October 15, the digital payments India ecosystem will undergo a period of adjustment. The impact on consumer spending UPI and merchant strategies UPI will depend on how stakeholders adapt to these changes. While the immediate focus is on cost distribution, the long-term success of UPI will hinge on maintaining its appeal as a seamless and cost-effective payment method. Both consumers and merchants must stay informed about these UPI payment changes to navigate the evolving landscape effectively.
Follow SouthAsianDesk on X, Instagram and Facebook for insights on business and current affairs from across South Asia.
Sources
- UPI MDR charges from October 15: Who will pay on transactions above ₹2,000? – thehindu.com
- UPI Charges To Be 0.4% For Some Payments Above Rs 2,000. Free For Consumers – ndtv.com
Image: th-i.thgim.com